San Diego Housing Market 2026: Home Prices, Mortgage Rates & 2027 Outlook
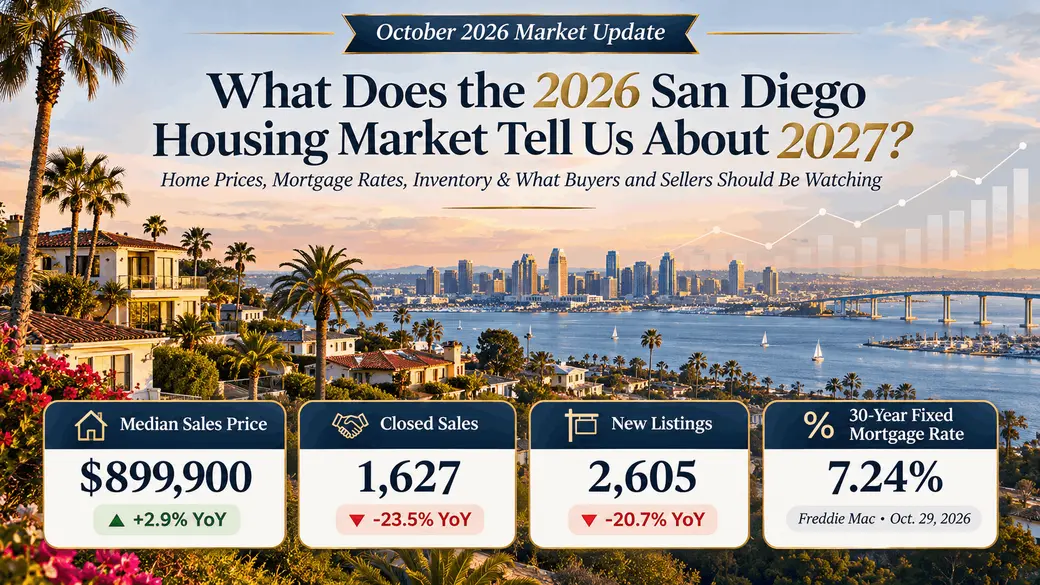
What Does the 2026 San Diego Housing Market Tell Us About 2027?
Home Prices, Mortgage Rates, Inventory & What Buyers and Sellers Should Be Watching
As we approach the end of 2026, one of the questions I hear most often is, "What's going to happen with the real estate market next year?"
It's a fair question, especially with everything we've experienced over the past few years.
We've seen historically low interest rates, rapidly rising home prices, affordability challenges, and changes in how buyers and sellers approach the market.
And depending on which headline you read, you might think home prices are about to take off again—or that the market is heading for a significant correction.
The reality? San Diego's real estate market is much more nuanced than either of those headlines suggests.
As we prepare for 2027, I thought it would be helpful to look at what the actual numbers are telling us and what they might mean if you're considering buying, selling, or simply keeping an eye on your home's value.
1. San Diego Home Prices Are Holding Up, but Sales Have Slowed
Let's start with the numbers.
According to the Pacific Southwest Association of REALTORS®, San Diego County recorded the following activity in October 2026:
| Market Indicator | October 2026 | Change From 2025 |
|---|---|---|
| Median sales price | $899,900 | +2.9% |
| Closed sales | 1,627 | -23.5% |
| Pending sales | 1,620 | -23.1% |
| New listings | 2,605 | -20.7% |
Source: Pacific Southwest Association of REALTORS®, San Diego County Market Statistics, October 2026.
What's interesting is that home prices have remained relatively resilient even as the number of transactions has slowed.
That tells us something important: Fewer homes are changing hands, but that doesn't necessarily mean home values are falling.
There's another distinction worth making. The median sales price measures the midpoint of homes that sold. It does not mean every home in San Diego appreciated by 2.9%.
The mix of homes selling can influence those numbers, which is why it's important to evaluate your specific neighborhood and property type.
2. Rising Mortgage Rates Are Affecting Buyer Affordability
One of the biggest influences on San Diego's housing market continues to be mortgage interest rates.
According to Freddie Mac's Primary Mortgage Market Survey, the average 30-year fixed mortgage rate was 7.24% as of October 29, 2026, compared with 6.17% during the same period in 2025.
While mortgage rates eased slightly from their mid-October peak of 7.40%, they're still considerably higher than they were a year ago.
What Does That Mean for a Buyer's Monthly Payment?
Let's use a $700,000 mortgage with a 30-year fixed term as an example.
| Mortgage Rate | Monthly Principal & Interest |
|---|---|
| 6.17% (October 2025) | $4,274 |
| 7.24% (October 2026) | $4,770 |
That's approximately $496 more per month, or $5,952 per year, for the same loan amount.
And remember, these figures don't include property taxes, homeowners insurance, HOA fees, or other housing expenses.
For perspective, a home purchased for $875,000 with a 20% down payment would result in a $700,000 mortgage.
In San Diego County, where home prices remain relatively high, even a one-percentage-point change in mortgage rates can significantly affect affordability.
How Does This Affect the Housing Market?
When mortgage rates increase, buyers may find themselves:
-
Qualifying for a smaller loan amount.
-
Adjusting their purchase price expectations.
-
Looking at different neighborhoods or property types.
-
Taking longer to make purchasing decisions.
-
Negotiating more carefully on price, repairs, or seller concessions.
-
Postponing their purchase until their financial situation improves.
Higher borrowing costs can also affect existing homeowners who are reluctant to give up their low mortgage rates, contributing to limited housing inventory.
Did Higher Rates Affect October's Sales Numbers?
It's reasonable to consider higher borrowing costs as one factor influencing buyer demand.
However, October's closed sales largely reflect purchase contracts negotiated during earlier weeks, so we shouldn't attribute the entire decline in October sales to the Federal Reserve's September rate increase.
Interest rates, affordability, inventory, consumer confidence, and seasonal trends all play a role.
The combination of higher borrowing costs and fewer transactions is certainly something worth watching as we approach 2027.
What Should Buyers Watch in 2027?
Rather than trying to predict exactly when rates will fall, I encourage buyers to evaluate several factors together:
-
The purchase price and available inventory
-
Their comfortable monthly payment
-
Potential seller concessions or rate buydowns
-
Long-term financial goals
-
The cost of waiting versus purchasing now
A lower interest rate doesn't automatically mean a better opportunity if increased buyer competition drives prices higher.
Likewise, purchasing at a higher rate only makes sense if the monthly payment is affordable today—not because refinancing might become possible later.
The goal is to make a sound financial decision based on today's numbers while remaining flexible about future opportunities.
3. Inventory Matters, but Not All Homes Are Competing in the Same Market
One of the biggest mistakes people make when evaluating real estate is treating San Diego County as one single housing market.
In reality, the market for a detached home in San Marcos can look very different from the market for a condominium in Vista or a coastal property in Carlsbad.
For example, September 2026 San Diego MLS figures showed:
-
Detached homes: Approximately 2.4 months of supply.
-
Condos and townhomes: Approximately 4.0 months of supply.
Months of supply measures how long it would take to sell the available inventory at the current sales pace, assuming no new listings were added.
Lower inventory generally gives sellers more negotiating leverage, while higher inventory can give buyers more choices.
These numbers suggest that detached homes remained in a tighter market than attached properties.
But even within those categories, neighborhood, price range, property condition, and competition make a difference.
What This Means for Sellers
If you're considering selling in 2027, understanding your direct competition will be essential.
A well-maintained, properly priced property may attract strong interest even in a slower market.
On the other hand, an overpriced home may sit while buyers compare it with better-valued alternatives.
Pricing based on what a neighbor received two years ago—or what an online estimate suggests—isn't necessarily a reliable strategy.
4. Buyers Have Become More Selective
One trend I've noticed in working with buyers and sellers is how carefully people evaluate the overall condition and cost of a property.
Today's buyers aren't simply looking at the list price.
They're also considering:
-
How much work the property needs
-
Insurance costs and availability
-
Property taxes and special assessments
-
HOA fees and financial condition
-
Roof, HVAC, and major system ages
-
Potential repairs or renovations
-
Whether the home meets their long-term needs
When monthly housing costs are already substantial, taking on an additional $50,000 in improvements can change the financial equation considerably.
That's why preparation matters for sellers.
It doesn't necessarily mean remodeling the entire house before listing. Sometimes smaller, thoughtful improvements and addressing deferred maintenance can have a meaningful impact.
The goal is to understand what buyers in your specific price range expect.
5. What About Homeowners Who Don't Want to Give Up Their Low Interest Rate?
This is an important consideration for many San Diego homeowners.
If you purchased or refinanced when mortgage rates were exceptionally low, you may be reluctant to sell and replace that loan with a higher-rate mortgage.
And I completely understand why.
But there are other considerations beyond your current interest rate.
Maybe you have more house than you need.
Perhaps you'd like to move closer to family, purchase a single-story home, reduce maintenance, or relocate to a less expensive area.
Or maybe your home no longer fits the way you want to live.
For some homeowners, staying makes the most financial sense.
For others, accumulated equity, a different purchase price, or lifestyle considerations may outweigh the benefit of keeping their current mortgage.
The important thing is to evaluate the cost of staying versus the cost of moving.
That includes looking at equity, selling expenses, replacement housing costs, property taxes, and financing options.
For homeowners age 55 and older, California's Proposition 19 may also create opportunities to transfer an eligible property tax base to a replacement primary residence.
The rules are specific, but it's another factor worth investigating.
6. Will San Diego Home Prices Go Up or Down in 2027?
I wish I had a crystal ball!
There are several factors that could influence the market next year.
Mortgage rates: Lower borrowing costs could bring more buyers into the market, but higher demand could also increase competition.
Housing inventory: More available homes generally give buyers additional options and greater negotiating leverage.
Employment and consumer confidence: Financial stability and expectations about the economy affect people's willingness to make large purchases.
Insurance and ownership costs: Rising expenses can influence both affordability and property values.
Local market conditions: Neighborhood-specific supply, demand, and property types will continue to matter.
Rather than focusing entirely on predicting the market, I think it's more productive to understand your options under different scenarios.
What would buying look like if rates stayed the same?
What if they increased?
What if your home sold for slightly less than anticipated?
Having answers to these questions can help you make decisions with greater confidence.
7. Thinking About Buying or Selling in 2027? Start Preparing Now
You don't necessarily need to make a move immediately, but gathering information early gives you more options.
If you're considering selling:
-
Understand your home's current market value.
-
Review your estimated equity and selling costs.
-
Identify improvements or repairs worth addressing.
-
Explore where you'd like to move next.
-
Compare the financial impact of selling versus staying.
If you're considering buying:
-
Review your financing and comfortable monthly payment.
-
Research neighborhoods and property types.
-
Understand taxes, insurance, and HOA expenses.
-
Identify your priorities versus your preferences.
-
Watch local inventory and recent comparable sales.
The earlier you begin gathering this information, the easier it becomes to recognize an opportunity when the timing is right.
Jaime's Take: The Best Time to Move Is When the Numbers and Your Life Make Sense
I've been involved in real estate transactions since 2001 and have been a REALTOR® since 2007.
Over those years, I've experienced very different market conditions, and one thing has remained consistent:
There's rarely a perfect market for everyone.
A market that creates an opportunity for one buyer may present challenges for another.
A homeowner with substantial equity and a low mortgage balance has different considerations than someone who purchased just a few years ago.
That's why I believe good real estate advice should begin with understanding your goals, not convincing you that now is always the right time to buy or sell.
If you're thinking about making a change in 2027, I'd be happy to help you look at the numbers, explore your options, and understand what makes sense for your particular situation.
And if you're perfectly happy right where you are, that's wonderful too!
I'm always available to answer questions about the North County San Diego real estate market, whether you're planning a move or simply want to stay informed.
Jaime Kull | REALTOR®
Coldwell Banker West | Ghio Panissidi & Associates
619-977-4838
JKSellsSD.com
JKSellsSD@gmail.com
DRE #01789582

Market statistics reflect information available in early November 2026. Mortgage payment examples assume a 30-year fully amortizing loan and exclude property taxes, homeowners insurance, HOA fees, and other expenses. Interest rates vary by borrower and loan program. This article is for general informational purposes and is not financial or tax advice.
Categories
- All Blogs (46)
- Accessory Dwelling Unit (1)
- CA ADU Law (1)
- Carlsbad Neighborhood (7)
- Community & Lifestyle (2)
- Encinitas Neighborhood (7)
- Escondido Neighborhood (7)
- financially prepare for wildfire (2)
- fire safety (1)
- Home Buying (3)
- home improvement roi (1)
- Home Maintenance (1)
- Home Selling (2)
- homeowner tips (7)
- homeowner wildfire insurance tips (2)
- homeownership (1)
- how to buy a home north county san diego (5)
- Increase Home Values in San Diego (2)
- Insurance tips (2)
- Local Living (2)
- Market Insights (4)
- Market Updates (2)
- Military Relocation (2)
- neighborhood guides (3)
- North County ADU (1)
- North County Home Buyers (5)
- North County San Diego homeowners insurance (1)
- North County San Diego Real Estate (9)
- North County San Diego Real Estate Market (1)
- Oceanside Neighborhood (1)
- Quarterly Market Update (1)
- Relocation (2)
- remodeling tips (1)
- San Diego ADU (1)
- San Diego Buyers (2)
- San Diego County Real Estate (9)
- San Diego Military Home Buying (5)
- San Diego Neighborhoods (6)
- San Diego North County First Time Home Buyers (3)
- San Diego North County Neighborhoods (6)
- San Marcos Neighborhood (6)
- VA Home Buyers (4)
- Vista Neighborhood (5)
- wildfire preparedness (2)
Recent Posts