Seller Credits and Rate Buydowns: A Different Way to Negotiate in Today's North County San Diego Market
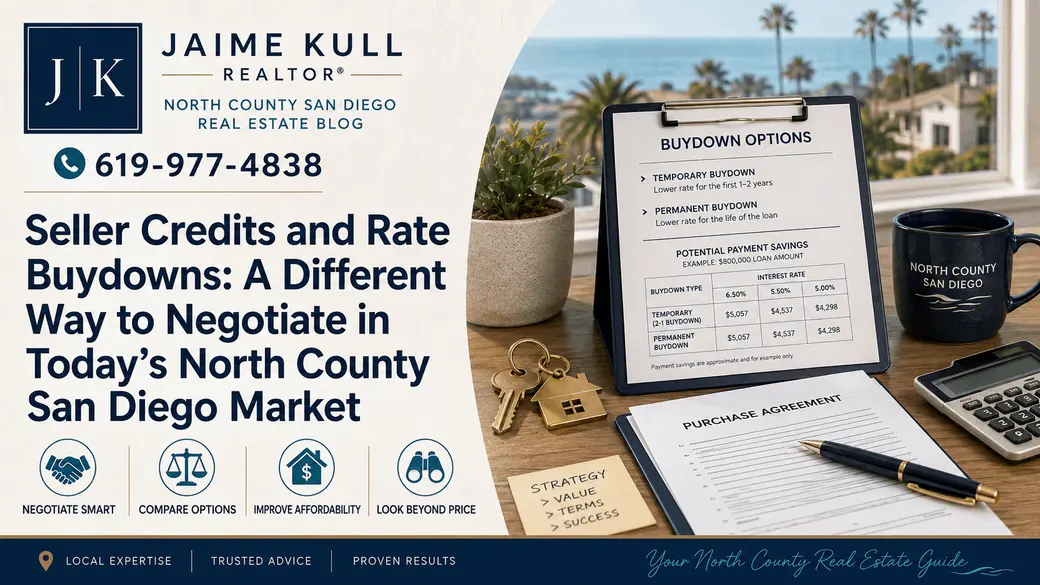
Seller Credits and Rate Buydowns:
A Different Way to Negotiate in Today's North County San Diego Market
When buyers and sellers negotiate a home sale, most people immediately think about one thing: price.
But in a market where mortgage rates are affecting affordability, changing the purchase price isn't always the only—or even the most valuable—way to structure a deal.
Seller credits, closing-cost assistance and mortgage-rate buydowns can sometimes give buyers meaningful financial relief while allowing sellers to negotiate without making a larger reduction to the sales price. The right strategy depends on the buyer's financing, the seller's goals and the individual property, but these tools are worth understanding in today's North County San Diego market.
What Is a Seller Credit?
A seller credit is money the seller agrees to contribute toward certain buyer expenses at closing.
Depending on the loan and transaction, those funds may be used toward allowable closing costs, prepaid expenses, discount points or an interest-rate buydown.
Fannie Mae refers to these types of contributions as interested-party contributions and places limits on how much can be contributed depending on the loan structure and down payment. Seller concessions must also be disclosed as part of the transaction.
In other words, this isn't simply the seller handing the buyer cash. It is a negotiated part of the purchase contract that has to fit within the rules of the buyer's particular loan.
Why Might a Buyer Prefer a Credit to a Price Reduction?
This is where the math becomes interesting.
Imagine a buyer is deciding between asking the seller for a modest reduction in the purchase price or asking for a comparable amount toward closing costs or a rate buydown.
A price reduction certainly lowers the amount being financed, but depending on the size of the reduction, the monthly payment difference may be relatively small.
A credit that reduces the buyer's upfront closing costs or temporarily reduces the mortgage payment may create a much more noticeable immediate benefit.
That's why the question shouldn't automatically be, “How much can we get off the price?”
Sometimes the better question is, “Where will the seller's dollars help this buyer the most?”
The answer is something the buyer should evaluate with their lender because loan programs, qualification and financial goals vary.
What Is a Mortgage-Rate Buydown?
A rate buydown uses funds to reduce the borrower's mortgage cost.
A permanent buydown generally involves paying discount points upfront to obtain a lower interest rate for the life of the loan.
A temporary buydown reduces the borrower's payment for a limited period before it increases to the full payment associated with the note rate.
For example, Freddie Mac permits certain temporary subsidy buydown structures in which the initial rate is temporarily below the note rate and then increases according to a predetermined schedule.
You may hear terms such as a 2-1 buydown, where the payment is calculated using an interest rate two percentage points lower during the first year, one percentage point lower during the second year, and then moves to the full note-rate payment afterward.
The specific structure and eligibility have to be approved by the lender.
The Important Catch With Temporary Buydowns
A temporary buydown can make the first year or two of homeownership easier, but buyers need to understand the eventual full payment.
This isn't a strategy where someone should purchase a home they can only afford during the discounted period and assume they'll refinance before the payment increases.
Refinancing may become an option if interest rates decline and the borrower qualifies, but there is no guarantee that rates will fall on a particular timeline.
The home should still make financial sense when the temporary subsidy ends.
Why Sellers Might Consider a Credit
From a seller's perspective, credits can sometimes help solve an affordability issue without making the same kind of visible price reduction.
Suppose a qualified buyer loves a property but needs help with closing costs or wants to reduce the initial mortgage payment. A negotiated seller contribution may help bring the buyer and seller together.
That doesn't mean sellers should automatically agree to every credit request. The offer needs to be evaluated as a whole.
A $900,000 offer with a $15,000 seller credit isn't economically the same as a $900,000 offer without one.
When comparing offers, sellers should look at the net proceeds, financing, contingencies, closing timeline and overall likelihood of the transaction successfully closing—not simply the number written on the purchase-price line.
Concessions Can Affect Comparable Sales Too
There's another detail homeowners may not realize: concessions can matter when real-estate professionals and appraisers analyze comparable sales.
Fannie Mae's appraisal guidance specifically identifies interest-rate buydowns, discount points and buyer closing costs paid by the seller as financing concessions that may need to be considered when evaluating comparable sales.
That's another reason why simply seeing that the house down the street “sold for $950,000” doesn't always tell the entire story.
The transaction may have included credits or financing incentives that affected the economics of the sale.
Price Is Only One Part of a Real-Estate Negotiation
Today's market rewards creativity—but also careful math.
For buyers, the strongest negotiation may not always be the biggest reduction in price.
For sellers, the strongest offer may not always be the highest headline number.
A seller credit, rate buydown, repair credit or other concession can sometimes create a transaction that works better for both sides.
The key is understanding what each dollar actually accomplishes.
Let's Run the Numbers Before You Decide
If you're buying or selling in North County San Diego, I'm happy to help you look at the complete offer rather than simply the purchase price. Working together with your lender, we can compare strategies such as seller credits, closing-cost assistance and rate buydowns and determine which structure makes the most sense for your situation.
In this market, good negotiation isn't always about getting the biggest price reduction. Sometimes it's about using the money more intelligently.
Categories
- All Blogs (41)
- Accessory Dwelling Unit (1)
- CA ADU Law (1)
- Carlsbad Neighborhood (7)
- Encinitas Neighborhood (7)
- Escondido Neighborhood (7)
- financially prepare for wildfire (2)
- fire safety (1)
- Home Buying (2)
- home improvement roi (1)
- Home Selling (2)
- homeowner tips (5)
- homeowner wildfire insurance tips (2)
- homeownership (1)
- how to buy a home north county san diego (5)
- Increase Home Values in San Diego (2)
- Insurance tips (2)
- Market Insights (3)
- Market Updates (1)
- Military Relocation (2)
- neighborhood guides (3)
- North County ADU (1)
- North County Home Buyers (5)
- North County San Diego homeowners insurance (1)
- North County San Diego Real Estate (8)
- North County San Diego Real Estate Market (1)
- Oceanside Neighborhood (1)
- Quarterly Market Update (1)
- Relocation (2)
- remodeling tips (1)
- San Diego ADU (1)
- San Diego Buyers (2)
- San Diego County Real Estate (9)
- San Diego Military Home Buying (5)
- San Diego Neighborhoods (6)
- San Diego North County First Time Home Buyers (3)
- San Diego North County Neighborhoods (6)
- San Marcos Neighborhood (6)
- VA Home Buyers (4)
- Vista Neighborhood (5)
- wildfire preparedness (2)
Recent Posts